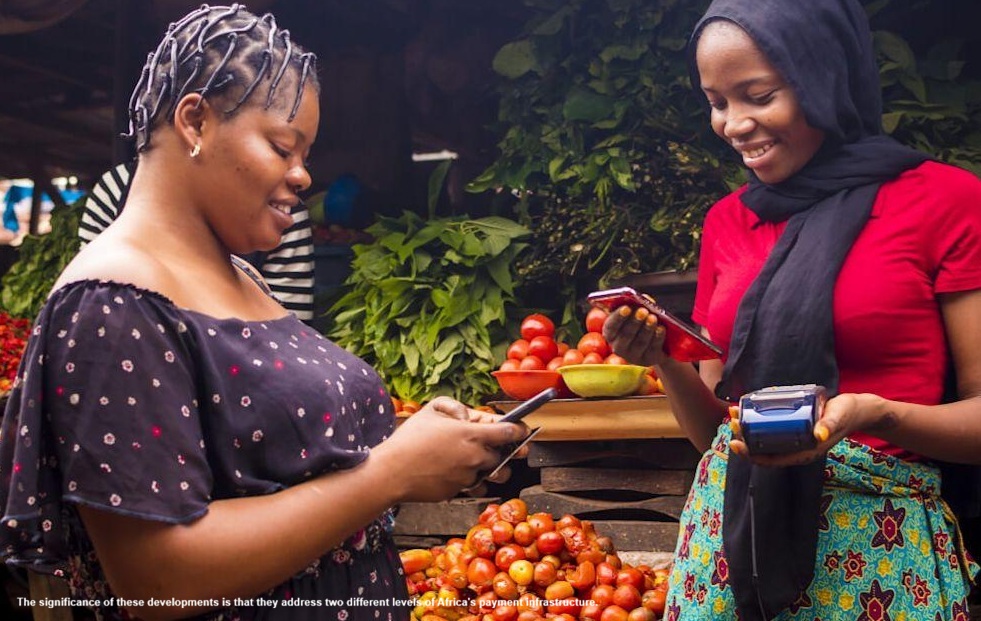
AFRICA CAN TRADE — BUT CAN AFRICA PAY AFRICA?
🌍 You’re reading Africa’s innovation network
EcoTech is a growing space for farmers, innovators, scientists, investors and contributors building practical sustainability solutions.
On 15 October 2026, Ethiopia's central bank joined the Pan-African Payment and Settlement System (PAPSS), extending the institutional reach of a network designed to facilitate cross-border payments in African currencies.
Reuters
On 16 October 2026, South Africa outlined plans to broaden direct access to its national payments system for qualifying non-bank providers, including fintech companies, telecommunications operators and retailers. Implementation is planned for 2027.
Reuters
These are separate initiatives, and South Africa's domestic reform does not mean it has joined PAPSS. Yet together they illustrate why Africa's trade integration increasingly depends on modernising the financial infrastructure that connects businesses and markets.
The Trade Agreement Is Only the Beginning
Africa has spent years establishing the foundations for greater economic integration.
The African Continental Free Trade Area (AfCFTA) represents an ambitious effort to reduce barriers between African markets, encourage regional value chains and increase trade among participating countries.
Its promise extends beyond moving more goods across borders.
It creates the possibility of African businesses becoming customers, suppliers, manufacturers and service providers to one another on a much greater scale.
Yet a trade agreement cannot, by itself, guarantee that a business transaction will be straightforward.
Consider a small Ethiopian manufacturer selling products to a distributor in Zambia.
The manufacturer may identify a buyer, negotiate a price and arrange transportation. But the transaction still depends on a reliable method of receiving payment.
If the payment must pass through several intermediaries, involve currency conversions or wait for international settlement, the business may encounter additional costs and uncertainty.
For smaller enterprises working with limited cash reserves, those difficulties can influence whether a transaction is commercially worthwhile.
Africa can reduce trade barriers at its borders, but regional integration remains incomplete if its businesses cannot pay one another efficiently.
Ethiopia Takes a Step Towards Continental Payment Integration
Ethiopia's entry into PAPSS marks an important development in the country's financial integration with the continent.
Developed through an initiative led by Afreximbank in collaboration with the African Union and the AfCFTA framework, PAPSS was launched commercially in January 2022 to facilitate cross-border transactions between participating financial institutions.
The system is designed to enable payments initiated in one African currency to be received in another, reducing the need for individual transactions to depend on conventional foreign-currency correspondent banking routes.
This does not eliminate exchange-rate conversion or the need for liquidity and regulatory compliance. Rather, it seeks to make the payment and settlement process more efficient.
By October 2026, Reuters reported that PAPSS operated across more than 15 countries and had over 150 commercial banks within its network.
The participation of Ethiopia's National Bank creates a foundation for deeper integration of Ethiopian financial institutions with the continental network.
However, central-bank participation should not be confused with every Ethiopian business immediately gaining access to all PAPSS services.
Commercial-bank onboarding, technical integration, regulatory requirements and availability to customers remain important implementation steps.
The broader direction is nevertheless significant: Africa is building financial connections intended to support the trade relationships it wants to expand.
Polity.org.za
Why Local-Currency Payments Matter
For many African enterprises, conducting cross-border business involves more than agreeing on a commercial price.
Businesses must also consider currency availability, bank charges, settlement times and the financial risks associated with delayed payments.
Historically, transactions between two African countries have sometimes depended on foreign correspondent banks or intermediary currencies, even when neither trading partner is located outside Africa.
This can create additional costs and operational complexity.
A more integrated African payment infrastructure could change that experience.
An importer could initiate a payment through a participating institution in its local currency, while the exporter receives funds through the relevant settlement arrangements in its own currency.
The transaction would still require foreign-exchange pricing, available liquidity and appropriate financial controls.
But the process could become more direct.
Potential benefits include lower transaction friction, faster settlement and improved predictability for businesses.
For an established multinational enterprise, payment delays may represent an inconvenience.
For a smaller agricultural exporter, engineering supplier or independent manufacturer, the same delay can determine whether wages, suppliers or transport expenses are paid on time.
Payment infrastructure is therefore not merely a banking issue. It is an enterprise development issue.
South Africa Begins Opening Its Domestic Payment Infrastructure
While Ethiopia is moving deeper into continental payment integration, South Africa is pursuing reforms within its domestic financial system.
The South African Reserve Bank's Payments Ecosystem Modernisation Programme is intended to improve competition, accessibility, resilience and efficiency in the country's payment infrastructure.
Historically, commercial banks have played a dominant role in directly accessing core national payment clearing and settlement arrangements.
Other payment-service providers have generally relied on banking relationships for access to parts of this infrastructure.
Under the planned reforms, qualifying non-bank organisations will be able to participate more directly, subject to the necessary regulatory and authorisation requirements.
This could create additional opportunities for fintech developers, payment providers, telecommunications businesses and retailers.
The reform is not an unrestricted opening of payment infrastructure.
Participants will still be required to satisfy applicable security, financial, operational and regulatory standards.
According to the Reserve Bank's modernisation programme, developments will include improvements to settlement infrastructure, broader payment interoperability and changes to the regulatory framework governing different payment activities.
A central component is the evolution of PayInc, formerly BankservAfrica, into a national payments utility that supports wider participation in shared digital payment infrastructure.
The reforms are intended to encourage innovation while maintaining the safety and reliability of the national payments system.
Reserve Bank
Competition Could Change the Experience of Small Businesses
The significance of South Africa's reforms extends beyond financial institutions.
For years, digital commerce has developed rapidly, while many smaller businesses have remained dependent on payment services with limited flexibility, varying charges or complicated integration requirements.
An expanded payment ecosystem could encourage greater competition among providers and improve access to digital transactions.
Potential applications include faster electronic payments, easier merchant acceptance, more interoperable payment services and improved financial tools for smaller enterprises.
The benefits are not guaranteed simply because additional participants enter the market.
Providers must still develop useful services, maintain strong security and offer commercially competitive products.
Consumers and businesses also need transparent fees, dependable dispute-resolution processes and confidence in how their financial information is protected.
Nevertheless, a more accessible payment environment can create opportunities for innovation.
For small businesses operating through digital marketplaces, e-commerce stores and regional supply networks, improvements in payment services can influence both customer experience and operating costs.
The ability to receive money reliably is fundamental to the ability to conduct business.
Two Reforms, One Larger African Opportunity
Ethiopia's PAPSS membership and South Africa's payment modernisation programme do not represent the same financial mechanism.
PAPSS concentrates on moving money across African borders through participating financial institutions.
South Africa's reforms concentrate on widening access to domestic payment infrastructure and modernising how financial services operate within the country.
Nevertheless, the two developments illustrate complementary requirements for a more connected African economy.
Efficient national payment systems are important for everyday commercial activity. Cross-border payment networks are necessary for businesses operating between different countries.
For African trade integration to become practical, both must function effectively.
An enterprise may operate successfully within its domestic market but encounter considerable difficulties when trying to collect payments from customers in neighbouring countries.
Similarly, a country may participate in a continental payment arrangement while smaller enterprises continue to struggle with access to affordable domestic financial services.
A connected African economy requires progress at both levels.
There is also an important distinction in the current situation.
As of October 2026, South Africa remains outside the PAPSS network, according to Reuters.
Its domestic payment reforms should therefore not be interpreted as an announcement of PAPSS membership or a confirmed timetable for joining.
That distinction matters because continental integration depends on actual operational connections, not simply the existence of compatible ambitions.
MarketScreener
Trust Must Travel With the Payment
Better payment infrastructure can reduce friction, but it does not automatically establish trust between trading partners.
A manufacturer receiving an order from an unfamiliar business in another African country still needs to determine whether that business exists, who is authorised to represent it and whether the transaction is commercially legitimate.
The buyer faces similar questions.
Will the supplier deliver the goods? Are the bank details correct? Can the parties verify contractual commitments? What happens if a dispute arises?
These questions demonstrate why payment innovation must develop alongside identity verification, enterprise recognition, secure documentation and appropriate commercial safeguards.
Modern payment networks already incorporate important financial controls.
PAPSS, for example, uses transaction validation, pre-funding and settlement arrangements designed to support secure transfers.
PAPSS
But verifying a payment instruction is different from verifying the wider commercial relationship behind the payment.
That distinction is particularly important for smaller African businesses entering unfamiliar markets.
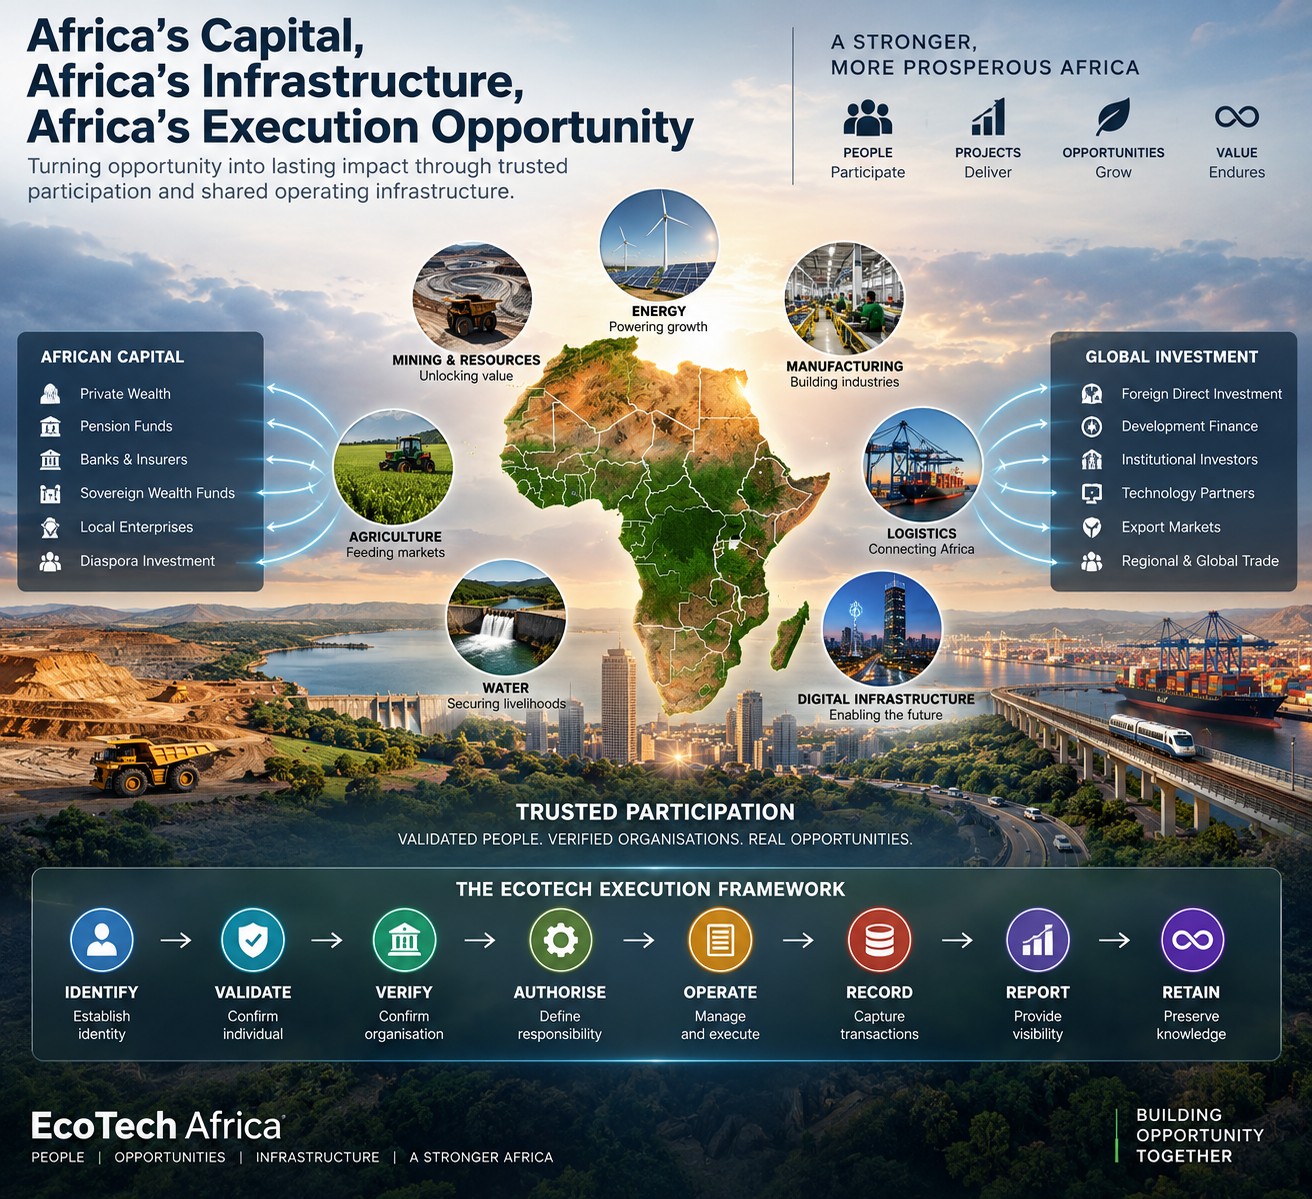
Reliable financial infrastructure must therefore form part of a wider system of trusted commercial participation.
The Opportunity for African Enterprises
Africa's payment developments create several possible opportunities across the commercial ecosystem.
Financial technology companies may develop services that help merchants receive payments more conveniently. Banks may expand partnerships with new providers. Digital marketplaces may eventually offer better cross-border transaction experiences.
Accounting, reconciliation and compliance services may become increasingly important as payment systems evolve.
For agricultural exporters, manufacturers, professional-service providers and small retailers, improvements could reduce the administrative burden associated with trading across borders.
However, enterprises should distinguish between available services and those still under development.
A financial technology company cannot assume that access to South Africa's national payment infrastructure will be automatic in 2027.
Similarly, a digital marketplace cannot assume that PAPSS currently supports every African currency, bank or destination.
The commercial opportunity lies in understanding the emerging systems, evaluating actual coverage and building services around verified capabilities.
The most valuable solutions will not necessarily be those that promise the widest reach.
They will be those that consistently deliver secure, affordable and reliable transactions for identifiable customers and businesses.
From Continental Agreements to Everyday Commerce
Africa's economic integration is often discussed through large agreements, investment programmes and institutional announcements.
Yet its success will ultimately be experienced through individual transactions.
A manufacturer in Ethiopia supplying a distributor in another African country.
A South African engineering enterprise purchasing specialised components from an African supplier.
A farmer cooperative receiving payment for produce delivered to a regional buyer.
A small digital business selling services across national borders.
Each transaction depends on an interconnected set of systems: commercial recognition, documentation, communication, logistics, payment and settlement.
When one element fails, the entire transaction can become difficult.
When those elements function together, regional trade becomes more accessible.
The recent developments in Ethiopia and South Africa suggest that the financial component of this wider infrastructure is receiving increasing attention.
The challenge now is to convert institutional progress into services that businesses can actually use.
The Next Step: Making African Trade Work
Africa has established an important ambition through the African Continental Free Trade Area: to strengthen commerce between African countries and create larger opportunities for African producers and enterprises.
But the ability to trade must be supported by the ability to transact.
Ethiopia's participation in PAPSS represents a step towards greater continental payment connectivity.
South Africa's planned domestic reforms could encourage wider participation, competition and innovation within one of the continent's major financial markets.
Neither development, independently, resolves the challenges of African trade.
Payment costs, currency liquidity, regulatory differences, financial inclusion, security and market access will continue to require attention.
Nevertheless, these reforms point towards a significant principle.
Trade integration cannot end at the border. It must extend to the financial systems that allow businesses to complete their transactions.
The next phase of African economic cooperation will depend not only on negotiating trade agreements, but on making them practical for the enterprises expected to use them.
Because a market becomes meaningfully connected when its participants can identify one another, establish commercial relationships, exchange goods and services, and receive payment with confidence.
Africa has begun building the framework for trading with itself. The next challenge is ensuring that Africa can pay itself — reliably, affordably and at scale.
Comments (0)
Join the Conversation
What do you think about this story? Share your view, a practical example, or a respectful challenge.
Comments are part of the EcoTech participation layer. Join from R49 once-off to participate, or log in if you already have an account.